EBITDA Growth Hits 50-Quarter High, PAT Growth Highest in 51 Quarters: Marico Share Price Jumps Over 6% in Sharpest Single-Day Rally in Over 2 Years
Karan / 03 Nov 2026 / Categories: Mindshare, Quarterly Results, Trending
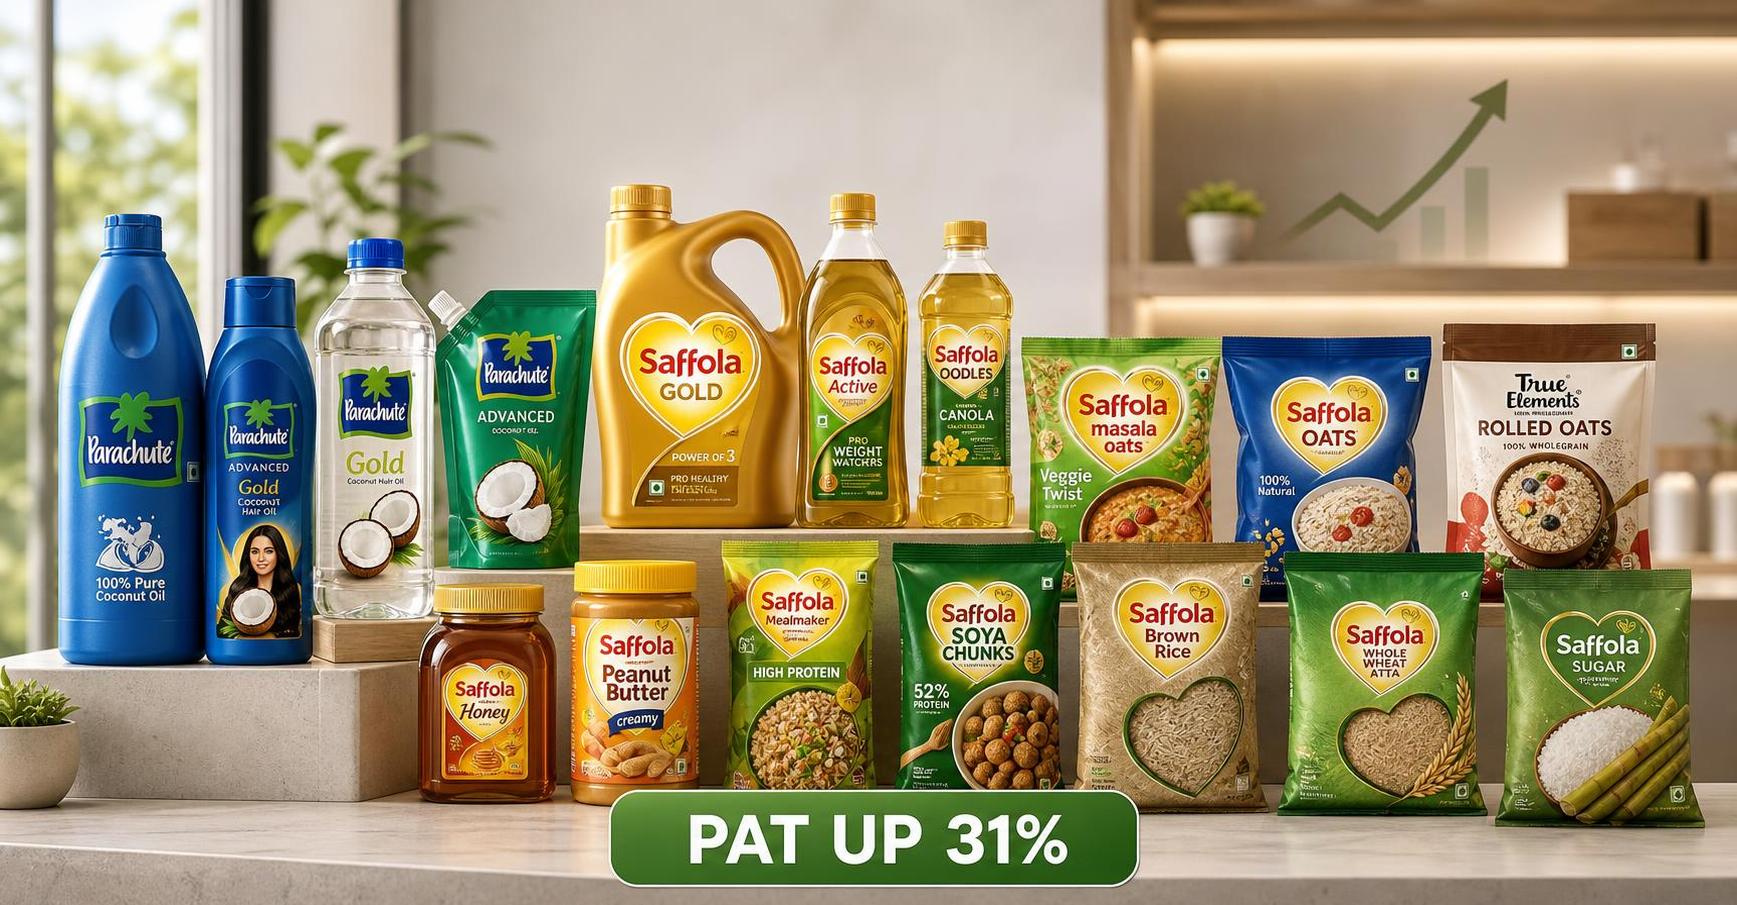
Marico’s consolidated revenue rose 13 per cent YoY to Rs 3,897 crore in Q2 FY27, while PAT climbed 31 per cent to Rs 550 crore as gross margins expanded sharply.
Marico has been pushing beyond its legacy coconut oil and edible-oil franchises through foods, premium personal care and digital-first brands, while managing volatile agricultural and crude-linked input costs. The consumer-products company reported a sharp improvement in profitability for the quarter ended September 30, 2026, with consolidated revenue rising 13 per cent YoY to Rs 3,897 crore and profit after Tax (PAT) increasing 31 per cent to Rs 550 crore.
Earnings before interest, tax, depreciation and amortisation (EBITDA) rose 27 per cent to Rs 709 crore. EBITDA margin improved by 2 percentage points to 18.2 per cent, supported by an approximately 6-percentage-point expansion in gross margin. Marico said this was its strongest EBITDA growth in 50 quarters and the highest PAT growth in 51 quarters.
The margin recovery came despite a 44 per cent YoY rise in advertising and sales-promotion expenditure to Rs 451 crore. Material costs increased just 1 per cent to Rs 2,022 crore, reflecting lower copra prices and a favourable portfolio mix. Employee costs rose 19 per cent, while other expenses increased 26 per cent, indicating that the company continued to invest in brands, distribution and newer categories rather than retaining the entire commodity benefit.
India revenue grew 10 per cent YoY to Rs 2,916 crore, driven by 10 per cent underlying volume growth. Parachute Rigids recorded 13 per cent volume growth, its highest in 22 quarters, although revenue growth was about 1 per cent after earlier price cuts to pass on lower copra costs. The brand's volume market share rose by more than 570 basis points to 60 per cent.
Value-added hair oils posted 21 per cent value growth, while the Foods portfolio grew 45 per cent and crossed an annualised revenue run rate of over Rs 1,500 crore. International revenue increased 23 per cent in rupee terms and 13 per cent in constant currency, led by Vietnam, the Middle East and North Africa, South Africa, and new country development and exports. For the first half of FY27, Marico reported 18 per cent revenue growth and 26 per cent EBITDA growth. Management expects teens revenue growth and mid-twenties EBITDA growth for the full year.
As of 9:25 am on November 3, 2026, Marico shares were trading at Rs 847.85, up 6.26 per cent from the previous close. The stock was about 4.2 per cent below its 52-week high of Rs 885.20 and had gained 9.7 per cent over one year, compared with a 6.52 per cent decline in the BSE 500 over the same period. The company's market capitalisation stood at about Rs 1,03,743 crore.
What This Means for Investors
The quarter supports Marico's strategy of combining core-brand volume growth with a larger contribution from foods, premium personal care and international markets. The 2-percentage-point EBITDA margin expansion is particularly significant because it was achieved alongside sharply higher advertising expenditure. This suggests that lower copra costs, stronger portfolio mix and operating execution are creating room to reinvest behind growth platforms. Project SETU 2.0 could further strengthen distribution, assortment and store-level execution, especially for foods and premium personal-care products.
The result is supportive for earnings visibility, but the sustainability of margin gains will depend on the balance between softer copra prices and inflation in crude-linked inputs, packaging and edible oils. Saffola edible-oil volumes also remain under pressure as Marico rationalises lower-return variants and channels. At 51.41 times trailing earnings and 36.75 times enterprise value to trailing EBITDA, the valuation places a high premium on continued delivery. Investors will watch whether new growth engines scale profitably and whether India volume growth remains robust after an exceptionally strong quarter.
Disclaimer: The article is for informational purposes only and not investment advice.