Net Worth: The Real Wealth Test
Ratin / 01 Oct 2026 / Categories: DSIJ_Magazine_Web, DSIJMagazine_App, MF - Special Report, Mutual Fund, Special Report
Imagine two individuals, both 35 years old, earning ₹24 lakh a year and living in the same city.
What comes to mind when you think of being wealthy or financially strong? For many people, the answer lies in the value of their property, the size of their annual income or the amount accumulated in their investment portfolio. But are these numbers enough to measure real financial progress? This is where ‘net worth’ comes into the picture. It looks beyond what you own and considers what you owe, helping you understand whether you are genuinely building wealth or simply accumulating assets[EasyDNNnews:PaidContentStart]
Imagine two individuals, both 35 years old, earning ₹24 lakh a year and living in the same city. Both have steadily increased their incomes, both invest regularly and both believe they are progressing financially. One proudly tells friends that he owns a ₹1.2 crore house, drives a ₹15 lakh car and has accumulated investments worth nearly ₹30 lakh. The other owns a smaller ₹90 lakh house, drives a modest car and has a somewhat larger financial portfolio. If the conversation stops here, it would be easy to assume that the first individual is financially ahead because the value of his assets appears significantly higher.
Now open their balance sheets. The first person has an outstanding home loan and vehicle loan of ₹85 lakh, while the second has a home loan of only ₹10 lakh. Once liabilities are deducted from assets, the picture changes. The first individual's net worth may be around ₹80 lakh, while the second could have a net worth of around ₹1 crore. The person who appears to own more may actually own less.
This is the financial distinction that often gets lost in the race to accumulate assets. Investors frequently celebrate the size of their portfolio, the value of their property or the number of investments they have accumulated, but these figures reveal only one side of the financial picture. The more meaningful question, therefore, is not simply how much do you own? It is how much wealth have you actually built after accounting for everything you owe? That is where the net-worth test becomes useful.
Beyond the Net Worth Number
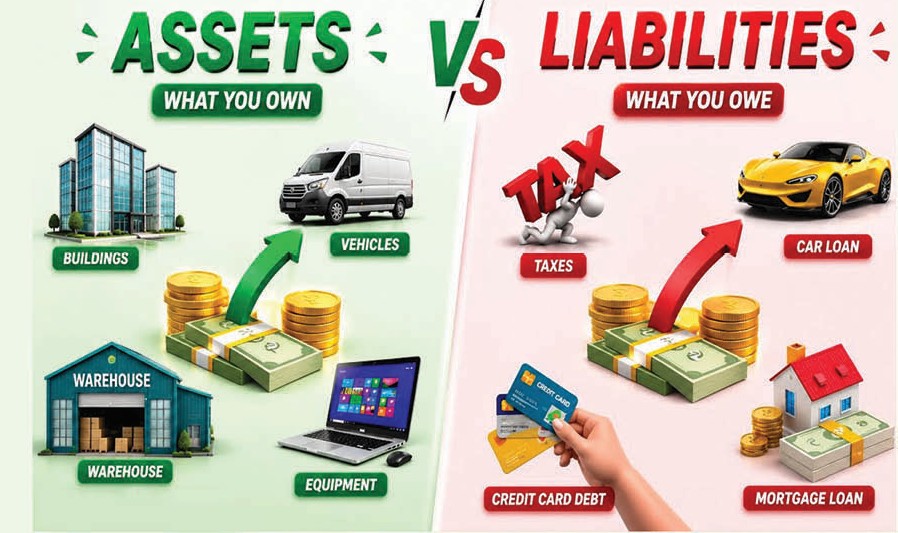
So, how can you calculate your actual net worth? The answer lies in a simple formula: Net Worth = Total Assets − Total Liabilities. Assets include equity shares, Mutual Funds, EPF, PPF, NPS, fixed deposits, Bank balances, gold, residential property, commercial property, vehicles and other possessions that have measurable financial value. Liabilities include home loans, vehicle loans, personal loans, education loans, creditcard outstanding amounts and other borrowings. The calculation looks elementary, but it can completely change the way investors look at their financial progress.

The calculation now becomes straightforward:
■ Net Worth = Total Assets - Total Liabilities ₹1.33 crore - ₹61 lakh = ₹72 lakh.
Therefore, although this investor owns assets worth ₹1.33 crore, his actual net worth is ₹72 lakh after accounting for the liabilities attached to those assets. This is an important distinction for investors. The value of everything you own is not the same as the wealth you have actually accumulated. A property valuation may show how much your house is worth, and a portfolio statement may show the current value of your investments, but neither tells you how much of that wealth is genuinely yours once outstanding debt is deducted.
A detail assesSMEnt, however, should not stop at the ₹72 lakh figure. The next question is what is driving that net worth? In this example, the investor has ₹80 lakh locked in his house, while his equity and mutual fund holdings amount to ₹25 lakh. This means a substantial portion of his wealth is concentrated in physical property rather than financial assets. That may be perfectly appropriate depending on his age, goals and housing needs, but it also means that his net worth and his readily accessible wealth are two different things.
The same analysis should be applied to debt. Borrowing is not necessarily a sign of weak financial health. A reasonably sized home loan can help a household acquire a property while allowing its income and investments to grow alongside the loan repayment. As the principal outstanding declines and the underlying asset potentially appreciates, the owner's share in that asset increases, thereby strengthening net worth.
The concern arises when borrowing primarily finances consumption or when liabilities begin growing faster than assets and income. A large car loan, repeated personal borrowing or persistent credit-card balances may increase the asset or consumption base without creating a corresponding source of future wealth. In such cases, the investor may appear financially well-off from the outside while the underlying balance sheet remains under pressure.
Therefore, calculating net worth should be viewed as the starting point of a financial health check, not the final answer. Once the number is established, investors should examine how much of that wealth is liquid, how much is concentrated in property or other physical assets, how much debt is supporting the balance sheet and whether the net-worth figure is increasing through regular savings and productive investments or simply through asset-price appreciation.
Not All Assets Build Wealth
The next question is more important than simply asking how much you own: “What kind of assets are actually building your wealth?” From an accounting perspective, a house, car, mutual fund portfolio, gold and fixed deposit all appear on the asset side of the balance sheet. But from a wealth-building perspective, they can behave very differently. Some assets have the potential to appreciate and generate income or compounding returns, while others gradually lose value or keep demanding money from your pocket.
Consider a ₹12 lakh car. The moment it leaves the showroom, its market value can begin to fall, and over the years depreciation can significantly reduce its resale value. At the same time, the owner continues to spend on insurance, maintenance, fuel and repairs. The car may be extremely useful and even necessary for the family, but financially it is primarily a consumption asset, not a wealth-creation asset. Compare this with ₹12 lakh invested in a diversified equity portfolio. Its value will fluctuate and there is no guaranteed return, but over a sufficiently long period, productive businesses can potentially grow earnings and shareholder value, allowing the investment to compound.
The same distinction can be applied to property. A primary residence may appreciate over time and can provide valuable stability, but it may not generate regular cash flow. A wellchosen rental property, on the other hand, may combine potential capital appreciation with rental income, although it also involves maintenance, Taxes, vacancies and other costs. Similarly, gold can play a role in diversification and wealth preservation, but it does not generate earnings or cash flows like a business or income-producing asset.
Liabilities deserve the same scrutiny. A home loan used to purchase a property that appreciates over time can be very different from high-cost credit-card debt used to finance consumption. The former can potentially help build ownership in an appreciating asset as the principal is repaid, while the latter can compound against the borrower through interest without creating a corresponding productive asset.
The objective, therefore, is not to label an asset as simply "good" or "bad". The better question is: “Does this asset strengthen my financial position over time, and does this liability help me acquire something valuable or simply increase my future financial burden?” The right balance depends on your age, financial goals, liquidity needs and risk capacity, but understanding how each item behaves can make your balance sheet far more meaningful.
How Healthy is Your Net Worth?
Once you develop the habit of looking beyond your assets and paying equal attention to your liabilities, the next step is to maintain the right mix of appreciating and depreciating assets and use debt prudently to acquire assets that can potentially strengthen your financial position over time. You should also track your net worth regularly rather than checking it only once every few years. The following parameters can help you evaluate the progress of your net worth, identify areas that may require attention and take corrective action when necessary.
■ The Debt-to-Assets Check
Debt-to-Assets Ratio = Total Liabilities ÷ Total Assets × 100
Suppose Household A owns ₹2 crore of assets and has ₹40 lakh of liabilities. Its debt-to-assets ratio is 20 per cent. Household B owns the same ₹2 crore of assets but owes ₹1.20 crore. Its ratio is 60 per cent. Both households can claim ₹2 crore of assets, but their ownership positions are very different. The ratio should not be treated as a universal pass-or-fail test. A young household that has recently purchased a home may naturally have higher leverage than an individual approaching retirement.
The nature of the debt, the interest rate, income stability, loan tenure and the underlying asset all matter. What becomes more useful is tracking the ratio over time. If assets rise from ₹1 crore to ₹1.50 crore while liabilities fall from ₹60 lakh to ₹40 lakh, net worth rises from ₹40 lakh to ₹1.10 crore. The balance sheet has strengthened from both directions. But if assets rise from ₹1 crore to ₹1.50 crore while liabilities simultaneously rise from ₹60 lakh to ₹1.10 crore, net worth remains at ₹40 lakh. The investor owns more assets, but has not actually increased net wealth.
■ The Financial Assets Mix
Financial Assets-to-Total Assets = Financial Assets ÷ Total Assets × 100
This ratio shows what proportion of your total assets is held in financial assets such as mutual funds, equities, bonds, fixed deposits, EPF, PPF and other financial investments. For instance, if a household has total assets worth ₹2 crore, of which ₹80 lakh is invested in financial assets, the ratio stands at 40 per cent. The remaining 60 per cent may be held in Real Estate, vehicles, gold or other physical assets.
The ratio can help you understand the composition of your wealth and how much of it is held in financial investments that can potentially generate returns or be accessed without selling a physical asset. A low ratio is not necessarily a sign of poor financial health, particularly when a large share of wealth is held in a home or other appreciating assets. However, tracking the ratio over time can help identify excessive concentration in physical assets and encourage a more balanced approach to wealth creation.
■ Wealth Built Against Income
Net Worth-to-Income = Net Worth ÷ Annual Income
Imagine two 40-year-old individuals who each earn ₹30 lakh a year. One has accumulated ₹90 lakh of net worth, while the other has accumulated ₹2 crore. Their current incomes are identical, but their financial foundations are substantially different. The first person's net-worth-to-income ratio is 3x, while the second person's is around 6.7x. There is no universal number that determines what this ratio should be at a particular age. A person who has recently moved into a higher-paying career may naturally have a lower ratio, while someone who has been earning and investing for two decades may have accumulated substantially more.
The real value of the ratio is in tracking personal progress. If income rises 10 per cent every year but net worth barely changes, it may indicate that additional income is being absorbed by lifestyle inflation, higher EMIs or consumption. On the other hand, if income rises moderately while net worth compounds steadily, the investor may be converting a growing share of earned income into long-term capital. That conversion is at the heart of wealth creation.
■ The Net-Worth Growth Check
Net Worth Growth = (Current Net Worth - Previous Net Worth) ÷ Previous Net Worth × 100
Net worth should not be viewed as a number that is calculated once and then forgotten. Tracking its growth over time can provide a clearer picture of whether your financial position is actually improving. For instance, if your net worth rises from ₹50 lakh to ₹60 lakh in a year, it has grown by 20 per cent. But the number becomes more meaningful when you understand what drove that increase. Was it higher investments, loan repayment, appreciation in property value or simply a temporary rise in market prices?
It is equally important to distinguish between genuine wealth creation and balance-sheet changes driven by leverage. If your assets increase by ₹20 lakh but liabilities also rise by ₹18 lakh, the improvement in net worth is relatively modest. Tracking this metric annually can therefore help you identify whether your income, savings, investments and debt management are collectively strengthening your financial foundation.

The Six-Month Test
Apart from these ratios, there is another way to assess the strength of your balance sheet: Imagine that your salary stops tomorrow and you have to manage your finances for the next six months.
■ Can you continue paying your essential expenses and EMIs without selling physical assets or liquidating long-term investments at an inconvenient time?
■ Do you have sufficient emergency reserves to handle an unexpected medical expense or family requirement?
■ Would you need to depend on a credit card or personal loan to bridge the gap?
■ Would your financial reserves allow you to avoid changing your long-term investment plan?
These questions reveal an important distinction between wealth and financial resilience. The answer depends not just on the value of your assets, but on their liquidity, the size of your liabilities, your investment income, your emergency reserves and your recurring financial commitments. A household may have a ₹3 crore balance sheet but very little accessible cash and substantial debt. Another may have ₹2 crore of net worth, a manageable home loan, adequate emergency reserves and a larger pool of financial assets.
The second household may have less headline wealth but greater financial flexibility. Again, the purpose is not to declare one balance sheet universally better. Different families have different priorities, responsibilities and financial goals. The purpose is to understand whether the wealth accumulated on paper can actually support those goals when circumstances change.
Net Worth is Not a Competition
There is one final trap worth avoiding. Net worth is a financial measurement, not a measurement of personal success. A 30-year-old who has recently started working may naturally have a modest net worth. A 55-year-old may have accumulated substantial assets over several decades. Someone may consciously choose to spend more on education, family, experiences or other priorities rather than maximise financial assets at every stage of life.
The usefulness of net worth lies in comparing your current balance sheet with your previous balance sheet, rather than comparing it with a friend’s, colleague's, or social-media influencer's financial claims. Ask whether your financial assets are growing, whether expensive debt is declining, whether your emergency reserves are adequate and whether your wealth is becoming more diversified. Examine whether your net worth is increasing through regular savings and compounding or merely because one physical asset has appreciated. These questions provide considerably more information than a headline number.
Conclusion
Ultimately, building wealth is less about owning more and more about strengthening what you already own. A growing salary, a larger investment portfolio or a valuable property can create the appearance of financial progress, but the real test lies in what remains after debt, financial commitments and other obligations are accounted for. A healthy balance sheet is one that can support your goals today while giving you room to deal with tomorrow’s uncertainties.
That is why net worth deserves to become a regular part of your financial routine. Review it periodically, understand what is driving the change and question whether your savings are translating into productive assets, whether debt is being managed sensibly and whether enough of your wealth remains accessible when required. Over time, these checks can reveal patterns that income or portfolio value alone may miss.
The objective is not to chase a bigger number. It is to build a financial foundation that becomes stronger, more flexible and more capable of supporting the life you want to create.
[EasyDNNnews:PaidContentEnd] [EasyDNNnews:UnPaidContentStart]
To read the entire article, you must be a DSIJ magazine subscriber.
[EasyDNNnews:UnPaidContentEnd]