3:1 Bonus and 1:5 Stock Split: 10 Shares of This MNC Stock Could Turn Into 200 Shares; Check Details
 Join Us
 Follow Us

Bosch Limited’s consolidated Q2 revenue rose 28.2 per cent YoY to Rs 7,655.1 crore, supported by passenger vehicles, commercial vehicles, two-wheelers and consumer-goods demand.
✨ Key Takeaways
Bosch Limited derives most of its revenue from mobility technologies supplied to vehicle manufacturers and the replacement market, making its performance closely tied to production volumes, technology content and automotive demand. The company reported consolidated revenue from operations of Rs 7,655.1 crore for the July-September 2026 quarter, up 28.2 per cent YoY, as growth accelerated across passenger vehicles, commercial vehicles, two-wheelers and consumer goods.
Earnings expanded alongside sales, although raw-material costs moderated the pace of operating profit growth. Earnings before interest, Tax, depreciation and amortisation, or EBITDA, rose 23.2 per cent to Rs 1,037.1 crore. Profit after tax, or PAT, increased 18.5 per cent to Rs 840.5 crore. The reported EBITDA margin was about 13.6 per cent, compared with roughly 14.1 per cent a year earlier, reflecting the impact of higher material costs.
The mobility business remained the principal driver, with quarterly sales rising 29.8 per cent to Rs 6,813 crore. Power Solutions grew 36.4 per cent and Vehicle Motion expanded 34.9 per cent, aided by demand in passenger-car and commercial-vehicle segments. Mobility Aftermarket sales increased 13.2 per cent, while the two-wheeler business rose 17.7 per cent on pre-festive original equipment manufacturer demand and a favourable product mix. Consumer goods sales, which include power tools and related products, increased 17.1 per cent to Rs 511.3 crore, supported by e-commerce and accessory sales.
For the first half of FY2026-27, consolidated revenue grew 25 per cent YoY to Rs 14,821.8 crore and EBITDA rose 20.6 per cent to Rs 2,015.9 crore. PAT declined 13.1 per cent to Rs 1,654.1 crore because the previous year included an exceptional gain from the sale of the Building Technologies business.
Bosch Chassis Systems India, which became a wholly owned subsidiary of Bosch Limited from July 1, 2026, reported quarterly revenue of Rs 1,506.2 crore, up 27.9 per cent YoY. Its Chakan facility also crossed cumulative production of 20 million units each of passenger-car anti-lock braking systems and two-wheeler anti-lock braking systems. Bosch said forthcoming Corporate Average Fuel Efficiency Phase 3 norms, scheduled for April 2027, could further raise demand for vehicle efficiency and safety technologies.
Bosch Stock Split and Bonus Issue
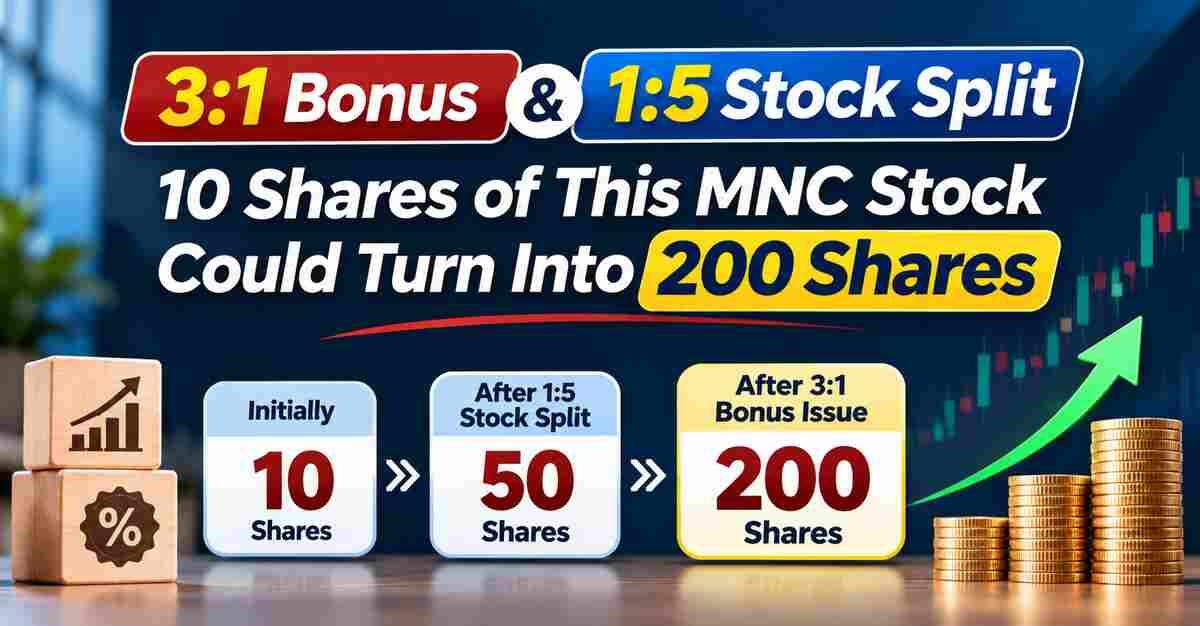
Bosch Limited's Board of Directors, at its meeting held on November 6, 2026, approved a stock split in the ratio of 1:5, under which each existing equity share with a face value of Rs 10 will be subdivided into five equity shares with a face value of Rs 2 each. The board also approved a bonus issue in the ratio of 3:1, offering three additional equity shares for every one equity share held after the split. Accordingly, an investor holding 10 shares before these corporate actions would hold 200 shares following the completion of both the stock split and bonus issue. The company stated that the proposed corporate actions are intended to encourage greater participation from retail shareholders. Both proposals are subject to shareholder approval, and the company expects to complete them within two months of the board meeting, subject to the necessary approvals.
As of 2:50 pm on November 6, 2026, Bosch shares were trading at Rs 50,623.50, down 3.48 per cent from the previous close. The stock was about 3.5 per cent below its 52-week high of Rs 52,450.00. Over one year, the shares had gained 35.75 per cent, compared with a 2.16 per cent decline in the BSE 500, highlighting the premium investors have assigned to Bosch’s growth, margins and technology portfolio.
What This Means for Investors
The quarter reinforces Bosch’s ability to capture a stronger automotive production cycle across several channels rather than through a single vehicle category. Growth in Power Solutions and Vehicle Motion points to rising demand from passenger and commercial vehicles, while the two-wheeler, aftermarket and consumer-goods businesses add breadth. The consolidation of Bosch Chassis Systems India also expands Bosch’s exposure to safety systems that are relevant across propulsion technologies. However, the slower rise in EBITDA than revenue shows that higher raw-material costs remain an immediate constraint on operating leverage.
The development is supportive for earnings visibility over the near term because the growth was broad-based and backed by higher technology adoption. Regulation-led opportunities from CAFE Phase 3 and future safety requirements could support content per vehicle over a longer horizon. Yet, execution will depend on sustained vehicle demand, material-cost management, localisation progress and the pace of customer adoption of newer technologies. At a trailing price-to-earnings multiple of 65.47 times, the valuation continues to place significant weight on durable growth and margin resilience.
Disclaimer: The article is for informational purposes only and not investment advice.