Rs 3,293 Crore Mega Bet: Solar Stock Nearly Triples Manufacturing Capacity
 Join Us
 Follow Us

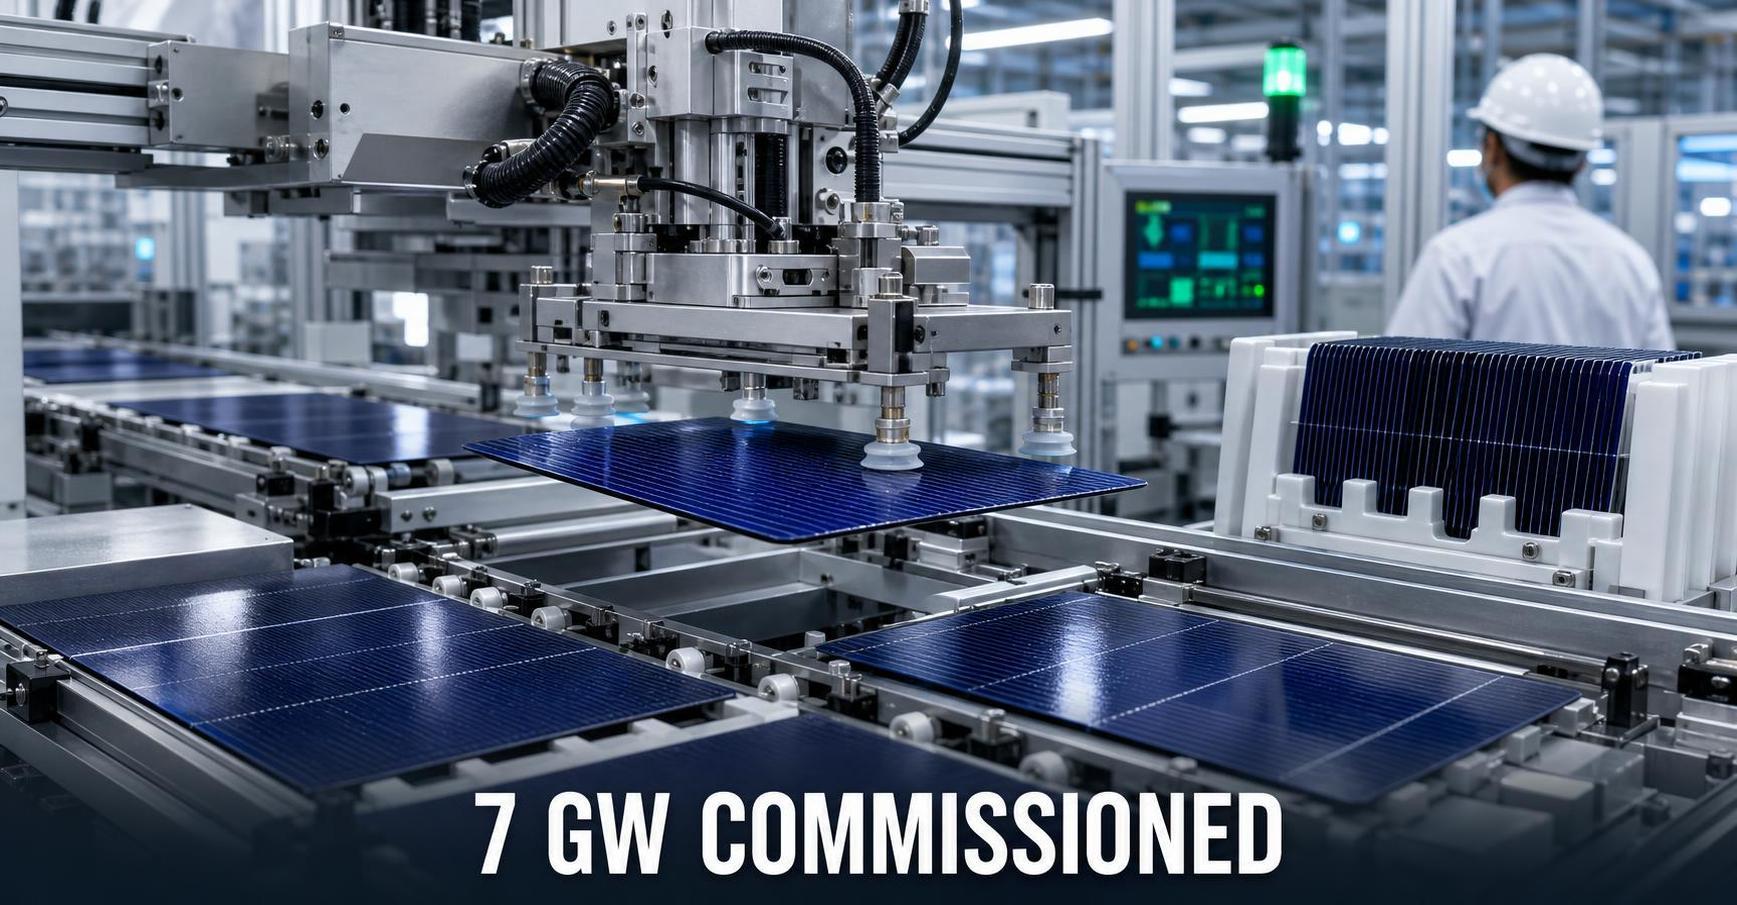
Premier Energies has commissioned its 7 GW N-type TOPCon solar cell facility at Naidupeta, expanding total cell capacity to 10.6 GW as it pursues deeper solar manufacturing integration.
✨ Key Takeaways
Premier Energies Ltd has commissioned a 7 GW N-type TOPCon G12R Solar cell manufacturing facility at Naidupeta in Andhra Pradesh, taking its total solar cell capacity to 10.6 GW. The company said the new facility makes it India’s largest solar cell manufacturer and represents a major step in its push towards an integrated domestic solar manufacturing platform.
The 101-acre plant has been built at a capital expenditure of Rs 3,293 crore and has begun trial runs after being completed on time and within budget. It is designed to manufacture around 88,000 solar cells an hour once operations stabilise, with average cell efficiency targeted at about 25.8 per cent.
Looking for High-Growth Stocks Below ₹100?
Explore DSIJ’s Penny Pick - a research-driven service focused on uncovering fundamentally strong low-priced stocks with long-term growth potential.
Download Service BrochureThe addition is substantial relative to Premier Energies’ earlier manufacturing base. The company had reported solar cell capacity of 3.6 GW at the end of FY2025-26. The Naidupeta line therefore takes its cell capacity to nearly three times that level, although commercial benefits will depend on how quickly the facility reaches targeted utilisation, yields and efficiency levels.
The plant uses N-type TOPCon G12R technology, along with artificial intelligence-based predictive performance analysis, process controls and automated material transport, packing and packaging systems. The line has also been designed to accommodate potential upgrades to TOPCon+ technologies, including poly-finger metallisation and advanced edge-isolation processes.
Managing Director Chiranjeev Saluja said the capacity addition had come at an important point for the company. ‘We remain positive on the outlook for orders, pricing and demand for high-efficiency solar products,’ he said, adding that the new line would improve supply reliability and operating efficiency as it ramps up.
The commissioning broadly delivers on the company’s earlier expansion roadmap. In its latest quarterly commentary, management had said the Naidupeta line was under advanced commissioning and expected utilisation to reach around 50 per cent to 60 per cent by November, with at least about 70 per cent targeted by the March quarter. That makes the production ramp, rather than the commissioning itself, the key operational monitor for investors.
Premier Energies is investing Rs 12,500 crore over three years to expand solar manufacturing capacity, establish ingot and wafer operations, and build businesses in inverters, Transformers and battery energy storage systems. The Naidupeta project alone accounts for roughly one-fourth of that announced investment programme.
Backward integration is particularly relevant in a domestic solar market where module capacity has grown faster than cell capacity. Premier Energies has said it intends to add 10 GW of ingot-wafer capacity in two phases by December 2027 and December 2028. The strategy is aimed at reducing exposure to imported inputs and improving cost competitiveness, though it will also keep the company in a high-capex phase.
The capacity increase follows a period of stronger financial performance. In the latest reported quarter, net sales rose 35.25 per cent year-on-year to Rs 2,462.59 crore, while profit after Tax increased 53.27 per cent to Rs 471.38 crore. Operating margin, however, moderated to 29.01 per cent from 30.11 per cent a year earlier, underlining the importance of achieving scale efficiencies at the new facility.
As of 9:42 am on September 21, 2026, Premier Energies shares were trading at Rs 901.80. The stock was down 9.58 per cent over the preceding year, compared with a 3.73 per cent decline in the BSE 500, and remained about 19.4 per cent below its 52-week high of Rs 1,118.45.
The company’s ability to convert Naidupeta’s trial production into stable commercial output, while managing pricing pressure in non-DCR modules and funding further integration projects, will determine how quickly the new capacity contributes to earnings.
Disclaimer: The article is for informational purposes only and not investment advice.